Robinhood Banking

Screenshots
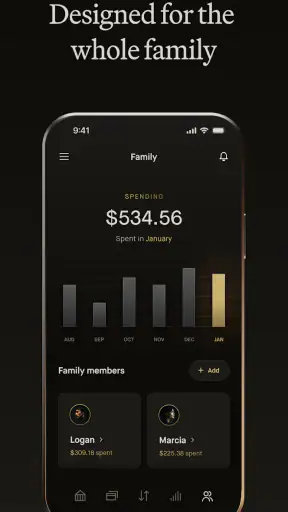
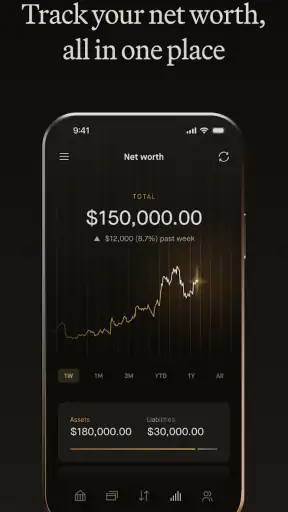
Details
- Rating
- 2.33K reviews
- Version
- 2.18.7
- Developer
- Robinhood
Analysis by Norviv
Managing money from a phone sounds simple until an app tries to combine everyday banking with the habits of an investing platform. Robinhood Banking takes that route. Developed by Robinhood, this free finance app focuses on bringing banking activity into the same mobile environment many people already associate with the company. I spent time looking at it as an everyday money tool rather than as a trading shortcut, and that distinction matters: its value is strongest when you want a clear, phone-first way to keep an eye on routine finances.
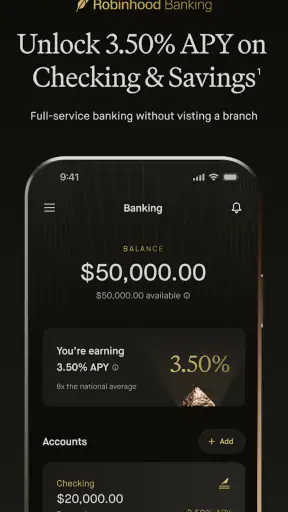
The central capability is the connection between banking access and a familiar Robinhood-style money experience. Instead of treating your bank account as a separate destination from the rest of your financial life, the app puts banking at the center of the workflow. That can make checking balances, reviewing activity, and making ordinary money decisions feel less fragmented. It is not automatically the best choice for every household, but it is appealing if you prefer handling financial tasks without moving between several unrelated apps.
Why the banking focus changes the everyday experience
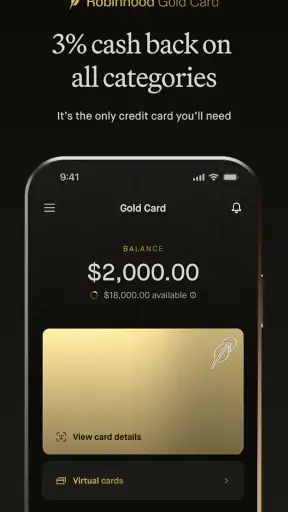
The app’s store summary describes it as “Credit Card & Banking,” while its short description presents it as Robinhood Banking. In practice, that positioning tells me where the product wants to compete: not merely as a place to watch investments, but as a more regular financial companion. The difference is important because a banking app is something you may open before paying a bill, checking whether a deposit arrived, or confirming how much room you have for a purchase.
That wider role makes the interface more consequential than it would be in an occasional-use finance app. When I open a banking tool, I want the important information to be easy to find and the next action to be obvious. Robinhood Banking benefits from a mobile-first design mindset, especially for people who dislike the cluttered menus and dated presentation found in some traditional banking apps. The trade-off is that a streamlined interface can sometimes leave experienced users looking for deeper controls or more detailed explanations.
I also think the app works best when you approach it as a central dashboard, not as a complete replacement for every financial service you use. A banking app can show you where money is moving, but it does not remove the need for budgeting discipline. If you regularly move money between accounts, manage shared household finances, or need specialized business banking tools, your decision should be based on those workflows rather than on appearance alone.
A realistic morning-to-evening use case
Imagine getting paid, buying groceries during lunch, and needing to check your available balance before an evening subscription renews. With Robinhood Banking, the useful part is the ability to perform those checks in the same place instead of opening a traditional bank app, a card app, and a separate financial dashboard. That reduces small points of friction. The savings are not dramatic in one session, but repeated every day, fewer app switches can make money management feel more manageable.
There is also a practical psychological benefit to seeing banking as an active part of your financial routine. If the app encourages you to check transactions soon after they happen, you may spot an unfamiliar charge or an unexpectedly large purchase earlier. That is not a substitute for careful account security, but it is a sensible habit. I would use the app’s quick access as a prompt for regular review rather than assuming that an attractive overview automatically means my finances are under control.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
How I would organize the first week
After installing it, I would not begin by moving every financial relationship into the app. I would first explore the account view, review how transactions are presented, and confirm that the information I care about is easy to understand. This is a useful first step with any banking product, but particularly with an app that tries to bridge everyday banking and a broader financial ecosystem.
My next step would be to watch one normal spending cycle. I would look for whether purchases appear in a way that makes sense, whether balances are clear, and whether the app helps me distinguish pending activity from completed activity. That distinction is easy to overlook when a balance changes quickly. A person who only checks the headline number may think they have more or less available money than they actually do.
For a more useful routine, I would pair the app with a simple weekly review. I would scan recent activity, identify recurring charges, and compare the account’s current position with the next few days of expected spending. This is one of the less obvious ways to get value from a banking dashboard: use it as a checkpoint for decisions, not just as a place to react after money has already left.
Where the app feels more convenient than a traditional bank app
Traditional bank applications often have the advantage of long-established account structures, but they can make ordinary tasks feel buried under menus. Robinhood Banking has a more direct appeal for users who prefer a modern mobile workflow and already understand Robinhood’s general approach. The app feels more natural for someone who wants to make quick checks throughout the day rather than sit down at a desktop and manage a large set of banking options.
Compared with a standalone budgeting app, however, the emphasis is different. A budgeting service may offer more elaborate category analysis, planning tools, or household-level views. Robinhood Banking is more useful when the immediate question is “What is happening in my account?” rather than “How should I design a detailed spending plan for the next year?” I would not choose it solely because I want advanced budgeting guidance.
Compared with a conventional bank, the choice also depends on how much support and institutional familiarity you value. A local or established bank may be a better fit if you prefer in-person assistance, branch access, or a broad range of specialized account products. Robinhood Banking’s strength is convenience within a mobile ecosystem, not the reassurance that comes from having every traditional service under one roof.
The small details that deserve attention
One useful habit is to treat notifications and account activity as separate layers of awareness. A notification can tell you that something happened, but opening the transaction history gives you context. I would avoid relying on a single alert as proof that a payment is fully settled. Checking the actual activity view before making a tight financial decision is a simple precaution that can prevent confusion.
Another worthwhile workflow is to use the app before a transfer or major purchase, not after. Looking at recent activity first can reveal pending charges that are easy to forget, such as a renewal or a card payment still being processed. This is a small but meaningful trade-off: the app can make checking easier, but it only helps if you build checking into your routine.
I would also keep a separate record of important financial commitments. A banking app is excellent for current account visibility, but a calendar or personal note can be better for remembering annual renewals, irregular bills, and upcoming obligations. This combination prevents the common mistake of expecting the transaction feed to act as a complete financial plan.
Where it fits, and where it does not
I’d use this section to weigh Robinhood Banking’s phone-first convenience against the needs that call for a more specialized bank or budgeting tool. The key distinction is whether a quick account check helps you make better day-to-day decisions, or whether you need deeper planning and support; next, I’d look at how that choice plays out when connectivity is part of the routine.
The main trade-offs before switching
The biggest limitation is that convenience can create overconfidence. A clean account screen may make money feel simpler than it really is. If you have several accounts, irregular income, shared expenses, or complicated tax responsibilities, you may need tools beyond what a mobile banking dashboard is designed to provide. Robinhood Banking can be part of that system, but I would be cautious about making it the only place where you understand your finances.
There is also a learning curve when a company known for investing becomes part of your everyday banking routine. Some users may appreciate the continuity, while others may prefer a strict separation between spending money and investment activity. That is not merely a design preference. Separating accounts can help people avoid using money intended for bills or short-term needs for riskier goals.
The app is free, which lowers the barrier to trying it, but “free” should not be the only deciding factor for a financial product. I would still read the relevant account terms carefully and consider whether the available banking arrangement matches my needs. The right question is not whether the app costs nothing to download; it is whether the overall setup is practical for the way I receive, spend, and organize money.
Support expectations matter too. Some people are comfortable resolving issues through an app, while others want a branch or a familiar local representative. If an account problem would cause serious disruption to your household, choose a provider based on the support experience you are prepared to use, not just on how polished the app feels during normal days.
Who will get the most from it
I see Robinhood Banking as a strong match for people who already prefer phone-based financial management and want banking to feel connected to the Robinhood environment. It can suit a user who checks balances frequently, values a straightforward overview, and wants to reduce the number of separate apps involved in routine money decisions.
It is also worth considering for someone who is building a more consistent financial habit. The app’s greatest practical benefit may not be a single advanced action; it may be the lower effort required to look at your money regularly. If that convenience helps you review spending every few days instead of ignoring your account until a problem appears, it has real value.
I would be more hesitant to recommend it as the only financial tool for a family managing shared budgets, a freelancer handling complex business cash flow, or anyone who depends heavily on branch-based service. Those users may be better served by a traditional bank paired with a dedicated budgeting application. Likewise, a person who wants sophisticated investment research should judge Robinhood’s investing products separately rather than assuming the banking experience answers that need.
Compatibility, reputation, and basic expectations
The app is listed for users aged Everyone and requires Android 7.0 or later, so compatibility should be comfortable for many Android owners with relatively recent software. It was released on March 19, 2024, and the current version is 2.18.7. I would still keep the operating system updated, especially for a finance app, because stability and security depend on more than the application package alone.
Its reception is notably strong, with a 4.9 average from around twenty-five thousand ratings and roughly two thousand reviews. It has passed one hundred thousand installs, which shows meaningful interest without making popularity a substitute for personal fit. I read those figures as encouragement to try the experience, not as a guarantee that every banking workflow will suit every user.
Robinhood is an established name in consumer finance, and that familiarity may make the transition easier for existing customers. Even so, I would keep my evaluation grounded in the actual banking tasks I need to perform. A recognizable developer can make an app easier to trust initially, but clarity, reliability, and suitable account terms matter more over time.
My recommendation after using the banking approach
Robinhood Banking is most convincing when convenience changes your behavior. If bringing banking into a familiar mobile environment makes you check transactions, question unusual spending, and plan around upcoming payments more consistently, the app earns its place on your phone. Its free access and approachable presentation make it easy to explore without committing immediately to a complete financial overhaul.
My recommendation is therefore specific rather than universal. I would suggest it to a mobile-focused user who wants a simpler daily banking checkpoint and is comfortable handling financial matters digitally. I would not present it as a universal replacement for a full-service bank, a detailed budgeting platform, or careful personal planning.
Before making it your primary banking destination, spend a week testing the tasks that actually matter to you: checking activity, understanding balances, reviewing recurring spending, and deciding whether the app gives you enough confidence to act. If those basics feel clear and the mobile workflow fits your habits, Robinhood Banking can be a practical addition to your financial routine. If you need specialized services, extensive household tools, or human support close at hand, the usual alternatives may remain the better choice.
Frequently Asked Questions
01What is Robinhood Banking, and what services does it offer?
Robinhood Banking is part of the Robinhood financial platform, designed to give users access to spending and cash-management features alongside investing services. Depending on eligibility and availability, users may receive a Robinhood debit card, direct deposit options, bill-payment tools, cash transfers, and interest on eligible uninvested cash. Features can vary by account type, location, and current Robinhood policies.
02Is Robinhood Banking safe and insured?
Robinhood uses security measures such as encryption, account authentication, fraud monitoring, and optional security protections to help safeguard customer information and funds. Eligible cash may receive protection through applicable FDIC insurance arrangements, while investments are generally covered under SIPC rules within their limits. Users should carefully review the specific insurance terms because not every balance or product has identical protection.
03Are there fees for using Robinhood Banking?
Robinhood Banking may offer several services without monthly maintenance fees, but that does not mean every transaction is free. Fees can apply to certain instant transfers, out-of-network ATM usage, expedited services, or other optional features. Before downloading or activating the service, review the current fee schedule in the app, since pricing, eligibility requirements, and available benefits may change over time.
04Can I use Robinhood Banking for direct deposit, bills, and everyday spending?
Eligible users can generally use Robinhood Banking for everyday financial tasks such as receiving direct deposits, spending with a Robinhood debit card, making transfers, and paying bills. However, availability may depend on identity verification, account status, and regional restrictions. It is also important to remember that Robinhood is not necessarily a full replacement for every traditional bank service, such as certain lending or branch-based services.
05What should I know before opening or downloading Robinhood Banking?
Before signing up, users should understand that Robinhood may require identity verification, personal information, and acceptance of its account agreements. Some features are limited by age, residency, account type, or regulatory requirements. The app combines banking and investing tools, so users should avoid confusing cash-management features with investment products and should review withdrawal rules, disclosures, and tax information before moving money.


